Saturday, August 31, 2019

GENM Q2 2019


  1. Revenue grew by 10.7% while gross profit grew by 7.1%. Gross profit margin and net profit margin remain stable at 25% and 12% respectively. 
  2. Other expenses increased by 32.8% as a result of the termination of contracts related to the outdoor theme park at Resorts World Genting of RM138.0 million (impairment).
  3. Impairment loss reduced by RM12 millions. 
  4. Finance cost increased by 72.6% as the company's bank borrowings increased. RM126 million accounts for 16% of its profit before tax. According to management, the increase of finance cost is due to lower qualifying assets eligible for interest capitalisation during the period, upon completion of certain projects under GITP
  5. Tax rate for 6 months cumulative was 13% in 2019 versus 16% in 2018. Tax rate were actually lower even after the tax rate hike. (I think there are still some tax incentive to cushion it)
  6. Profit after tax were lower by 8.8% which we will explain later. 


  1. Revenue from Malaysia increased by 15% however it EBITDA only increased by 2% due to higher casino duty however it is offset by higher revenue and lower payroll and related expenses as a result of reduction in the number of employees.
  2. Revenue from UK & Egypt dropped by 1% however its EBITDA increased by 43% due to impact of adopting MFRS 16 and was partially offset by lower debts recovery in 1H 2019.
  3. Revenue from US and Bahamas increased by 8% while its EBITDA increased by 18% due to the strengthening of USD against RM. Excluding this impact, revenue would have increased by 3% mainly due to higher volume of business from RWNYC operations.. 
  4. Main reason for profit before tax to decrease is due to higher pre-opening expenses of RM112 millions due to provision for termination related costs relating to the outdoor theme park of RM138.0 million,  and lower interest income of RM112 millions due to impairment of the Group’s investment in the promissory notes issued by the Tribe in 2018. 

  1. Cash at bank reduced by RM 1,022 million while bank borrowings increased by RM 2 million. Main reason for the cash to reduce was for purchase of PPE amounting RM1579 million. 

  1. The theme park is expected to open soon which can mitigate the increase in tax rate hike in malaysia. 
  2. Genm will continue to reduce its operating cost by improving efficiency. 
  3. First phase of group expansion at RWNYC will open and increase in business in NYC should be able to mitigate or cushion the losses from Empire Resort next year. 


Comments:

  1. Genm business is still growing proven by its increased revenue and gross profit (organic growth).
  2. Gearing ratio of the company increased from 9% to 15% and its finance cost increased significantly which can post as a risk to the company's ability to distribute special dividend. 
  3. The opening of theme park should boost its business and mitigate the losses from Empire Resort however the cash of the company would further deteriorate after acquiring Empire Resort which might affect the company's ability to distribute special dividend.
  4. Valuation wise, i think at currect price of RM3.12 its PE is only 13.5 which is still way below its reasonable PE of 18. At PE 18, Genm is worth RM 4.32. 


Thursday, August 22, 2019

Ptrans Q2 2019

  1. Gross profit improved to 42.48% cumulative quarters in 2019 VS 39.85% in 2018 (well done to the team for controlling the COGS effectively).
  2. Revenue increased by 3% however its general and administrative expenses dropped by 0.3% (another thumbs up to the management team for controlling the admin expenses so well).
  3. Other operating income was higher by 138% or RM 2.2 million due to higher rental income from rental of construction equipment. 
  4. Finance cost is higher this quarter and accounts for 20% of profit before tax as their bank borrowings was higher. Although the company's bank borrowing was higher, however the gearing ratio actually dropped from 64% to 62% which is good. 
  5. Profit before tax improved by 23% however profit after tax only improved by 1.8% due as cumulative quarters for 2018, there is a tax income of RM 2.7 million. Nevertheless, the tax rate for the current quarter is only 3.3%.
  6. Although the company has higher net profit, but its EPS dropped by 9.7%. This is due to increase in number of shares result from warrant conversion. Number of shares increased by 6.2%.


  1. Cash flow from operating is higher at RM 17 million compare to RM 13 million previously. 
  2. Cash from used in investing is lower at RM 15 million compare to RM 38 million previously. 
  3. From the above calculation, we can conclude that with higher operating cash flow and lower investing activities, PTRANS is able to generate more free cash flow moving forward to pair down its debts as well as used for dividend payout. 


  1. Revenue was higher by RM 4 million for its terminal operations however operations from petrol station and buses are slightly lower by 10% and 0.9% respectively. 


  1. Q2 usually serves as the strongest quarter for PTRANS as there are more long weekends, public holidays and school holidays. 


  1. Terminal Kampar has commenced its terminal operation at the end of 2nd quarter. Meaning we could see its contribution at the end of second quarter of 2019. 


Comments
  1. Better efficiency is seen from the company profit and loss account for the cumulative quarters in 2019.
  2. Balance sheet becomes stronger as PTRANS has a free cash flow of RM4.6 million for cumulative quarters in 2019. As long as if the company do not immediately start its 3rd terminal project, i believe PTRANS could pair down its debts and further strengthen its balance sheet in a short period. 
  3. The only uncertainty now is when the revenue and expenses from terminal kampar kicks in next quarter, will the overall company earnings being lifted or dragged lower? 
  4. However according to Affin Hwang report: Terminal Kampar’s ground floor operations — comprising bus services, advertising and promotion as well as rental of four shoplots and eight kiosks — have kicked off with a 90% occupancy rate, while the overall expected take-up rate from prospective tenants for the entire mall stands at 70%.Furthermore, most of the anchor tenants — cineplex, gym, bowling alley and supermarket — have been secured.
  5. If Terminal Kampar will generate some good cash flow, then the additional shares from warrant conversion and high gearing ratio would not be an issue. 
  6. Assuming if PTRANS have an full year EPS of 2.52 sen, a 35% dividend payout will be 0.89 sen. PTRANS has paid out 0.25 sen in Q1, therefore expecting another 0.64 sen to be paid out in Q3. At current price of RM 0.195, DY is set to be 4.5%
  7. Valuation wise, for 2.52 sen of EPS a year, its PE at RM 0.195 is 7.7 which is deemed to be undervalue if Terminal Kampar is lifting its earning. 


Tuesday, August 13, 2019

Genm acquire 46% of Empire Resorts with RM 540 millions and its Impact on Genm Financial


  • Genm is acquiring 46% of Empire Resort for RM 540 millions. 

Financial Highlights for Empire Resort in 2018 & 2019
  • According to Bloomberg, Empire Resort losses USD 140 millions (RM 590 millions) in year 2018 which is the highest over the past 4 years. 
  • Empire Resort losses USD 36 millions (RM 150 millions) in Q2 2019. Assuming Empire Resort incurred the same losses in Q3 & Q4 2019, that would be a loss of USD144 millions (RM 600 millions). 
  • Genm acquire 46%, meaning RM 276 millions of the losses will impact on Genm result. 


Financial Highlights for Genm in 2019
  • Genm generates profit after tax of RM 253 millions in Q1 2019. Assuming if Genm consistently generates the same amount over the remaining quarters, profit for 2019 would be RM 1012 millions. 
  • However do take note that there is a one off pre opening expenses of RM 210 millions and one off gain on disposal of RM 123 millions in Q1 2019. I do not expect this expenses to appear in Q2 2019, therefore, Q2 2019 result are expected to be better. 
  • If exclude the pre opening expenses and one off gain on disposal, Genm profit after tax should be RM 369 millions. Therefore, a full year estimation would be RM 1476 millions.


Impact of Empire Resorts losses on Genm Financials

Scenario 1 (pessimistic) 
  • RM 1012 millions - RM 276 millions = RM 736 millions
  • RM 736,000,000 / 5,659,071,000 shares = EPS 13 sen for year 2019
Scenario 2 (optimistic)
  • RM 1476 millions - RM 276 millions = RM 1200 millions
  • RM 1,200,000,000 / 5,659,071,000 shares = EPS 21 sen for year 2019


Valuation
  • At RM 3.12 a share, PE of Genm is 14.8 assuming the EPS is 21 sen.
  • At RM 3.12 a share, PE of Genm is 24 assuming the EPS is 13 sen.
  • A fair PE of Genm should be around 15 - 17. 

Key Things to Ponder
  • Will the reopening of theme park in end 2020 or early 2021 cushion the additional losses contributed by Empire Resort?
  • Will the voluntary bankruptcy debts restructuring under chapter 11 help Empire Resort to reduce its debts hence reduce its losses? 
  • The core value of Genm is that it is the only casino in Malaysia and Genting remain as one of the most popular tourist destination/short get away for Malaysian due to its weather and portrait as an all rounder to entertain family from adults to kids. Has the core value of Genm being broken at this stage? 
  • More over, Genm has been consistently generating a positive cash flow from operating amounting RM 1500 millions to RM 2000 millions every year . How massive is the impact of RM 300 millions of losses from Empire resort? RM 300 / RM 1500 = 20%. 
  • Share Price of Genm before the news announcement is RM 3.61. RM 3.61 discounted by 20% would be RM 2.88. Therefore, RM 2.90 should serve as a very strong support fundamentally. 

Saturday, July 6, 2019

AEONCR Q1 2020

  1. Aeoncr achieved a record high revenue of RM 378 million for the current quarter which accounts for approximately 28% of 2018's revenue. 
  2. Although the revenue recorded as a best quarterly revenue in Aeoncr history, its net profit margin shrink to 22.3% as compared to its benchmark of 24% due to higher finance cost and higher impairment loss on receivables (Finance cost accounts for 90% of its net profit; impairment loss on receivables are RM 93 million which accounts for 30% of 2019 impairment on receivables) Without this additional RM 36 million of impairment loss and RM 27 million of  finance cost, Aeoncr would actually achieve a RM 147 million of net profit which is a record high as well. 


  1. Its financing receivables grows by 5.52% however its borrowings grows by 8.02%. Its revenue also grows by 5.21% as compared to its proceeding quarter. (nothing much significant here, everything is in line)

  1. Nothing much being mentioned in its prospects, however the company mentioned that it is able to maintain its performance for 2020. 


Comments
Overall, Aeoncr delivery a very good quarterly result with record high quarterly revenue. Although it recorded a lower net profit as compared to previous quarter, however, if we exclude its additional impairment loss on receivables of RM 37 million, Aeoncr actually achieved a net profit of RM 120 million, that translates into EPS of 47 sen. Therefore, it is important for us to look at its next quarter result to see if there is additional impairment on receivables. If there is no more, there shouldnt be any issue for Aeoncr to deliver a better performance for year 2020. 

It is also worth taking note that NPL for Aeoncr right now is 1.92% which is even lower than NPL for 2019 of 2.04%

Valuation wise, Aeoncr is currently trading at PE of 12.3 at the price of RM 16.70 which is deemed to be a record high PE. At PE of 11, Aeoncr is worth RM 14.31. However, as mentioned above if we exclude the additional impairment loss of RM 37 million, at PE of 11, Aeoncr is worth RM 15.96.


Friday, June 7, 2019

Elsoft Research Berhad (AR 2018)

Corporate Profile
  • Elsoft Research berhad had 4 main subsidiary being STSB, ESSB, LESO and BHSB. (Althought Elsoft is a tech company but it also invest in a butterfly farm in penang. Its Butterfly House Sdn Bhd (BHSB) made a losses of RM 1.22 million in 2018 and RM 0.98 million in 2019).
  • Elsoft Research Berhad is a leading provider of LED test and burn in system. It provides cost effective automated test equipment (ATE) to semiconductor, optoelectronic and automation industries. Its key product are test and burn-in systems used by its customers who manufacture optoelectronic devices such as LED, image sensors and automotive lightings to test their products before launching into the market.
  • Elsoft business can be categorized as below:-
    • Selling of automated LED test equipment (test equipment to check LED for automobiles and smartphones)
    • LED tester and LED burn in system (test system to check the lighting features of smartphones and automobiles)
    • Industrial IO board
    • Solar cell tester
    • Embedded controller for medical device (to be launched by end of 2019 or early 2020)
  • The smart device contributes 68.7% of its revenue followed by general lighting (14.6%) and automotive (13%).
  • 65% of Elsoft's staffs are engineers. This means the minimum wage scheme will not impact the company and shows that the company is heavily invested in R&D. 


Financial Highlight
  1. Elsoft's revenue, PBT and net profit grew at CAGR of 20.75%, 23.52% and 24.22% respectively from 2013 - 2018. ( This is due to high demand from smart devices industry over the years as well as most cars nowadays are switching to LED lights). 
  2. Elsoft has very high gross profit margin and net profit margin (> 50%) which i think is because they invent (original manufacture design, ODM) their own automated testing equipment for LED (this is their main competitive advantage. Elsoft do not push their product or services by participating in price war)
  3. Elsoft has been consistently reinvest approximately 20% - 25% of their net profit or 10% of their revenue in research and development over the years which is consider fair for a technology company. 
  4. Elsoft has a dividend payout policy of 40% of its net profit however, it has been consistently distributing more than 70% of its profit to its shareholder since 2015, which is double of what it promised (this showing that the management is willing to share its profit with its shareholder)
  5.  ROE were more than 25% since 2014 and reach its peak of 35% in 2018 (Economies of scale with large scale production during the year had improved the overall product margin hence improved their return to equity
  6. Elsoft is a net cash company with zero borrowings. Its net cash per share was 11 sen (Its share price is currently RM 0.805 where 11 sen of it were cash).
  7. From its operating cash flow from 2013 - 2018, we can see that Elsoft is able to convert most of its net profit into cash. 

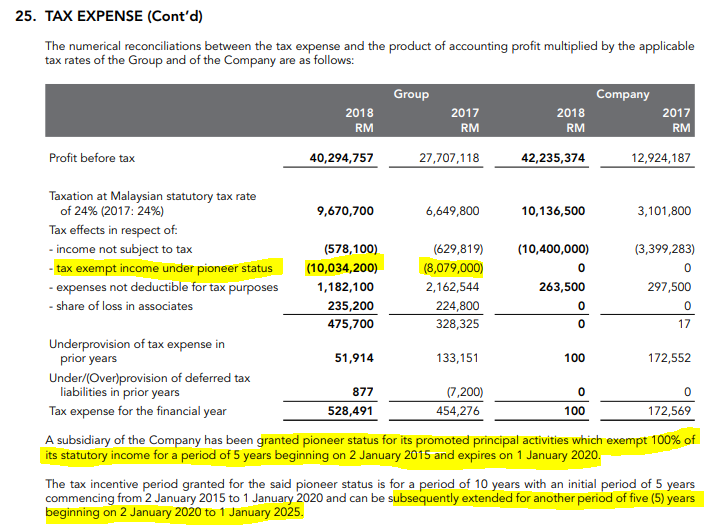
  • Elsoft's subsidiary (Elsoft System Sdn Bhd) enjoy tax exemption  of 100% under pioneer status until January 2025. This allows the company to save RM 10 millions of income tax (Elsoft paid RM 528k of income tax for its PBT of RM 40 million, this translate into 1.3% of income tax rate).
  • Elsoft derive its revenue mainly from Malaysia (85%) followed by China (13%). 
  • One of its major customer contributes RM 58 million or 75% of its total revenue however the management indicated that they have been working with this major client (lighting solution MNC) for more than 15 years indicates a long term and stable business relationship. 


Future Prospect
  • According to publication released by Semiconductor Trade Statistic the demand for semiconductor was up 13.7% in 2018 and expected to slow down by 3% in 2019 and to pick up again in 2020.
  • The above data is in line with Elsoft earnings as the demand weaken for the beginning of 2019 and expected to pick up during 2nd half of 2019. Maybe to recover in 2020.
  • Moving foward, Elsoft's R&D will be focusing on 
    • (a) ATE for infrared/laser devices testing 
    • (b) Next generation ATE for smart devices industry (LED flash tester catered to a major smartphone brand’s upcoming product line)
    • (c) New ATE for automotive industry (headlamp tester - developing a new range of test equipment to test multi-beam digital headlights that are replacing single-beam LED headlights operating on a rotating mechanical system for the automotive industry.)
  • Elsoft is also diversifying into embedded controller for medical device industry in 2019 which expect to be out in late 2019/ early 2020(however, this wont contributes significantly to the company to begin with).


As at Q1 2019
  • Gross profit margin dropped to 49% for the first quarter as compared to 58% in 2018. 
  • The business dropped 40% due to lower demand for automated test equipment (ATE) which is same as what 2018 annual report mentioned (i am expecting the 2nd quarter 2019 to be bad as well).
  • Although the business in Malaysia dropped 64% but the company has expanded further into overseas market. 
    • China contributes RM 3 million of revenue for Q1 2019 vs RM 10 million for 2018.  
    • Other countries contributes RM 1.1 million for Q1 2019 vs Rm 928k for 2018. 

  • The management didn't reveal much on its prospect however i think it is quite hard for 2019 to be a performing year. 
  • According to the analyst from TA Research, the company currently has an order book of RM 20 million (This only translate to 25% of 2018 revenue).  


Strength
  • High profit margin proving the company's strength in R&D (highest profit margin in the industry). 
  • Reliable management as the company is willing to share 80% of its profit with its shareholders although the dividend payout policy is only 40%. 
  • Elsoft never has a loss making quarter since 2009 and never fail to payout dividend since 2009. 
  • Enjoy low income tax rate due to pioneer status until 2025.


Weakness
  • Elsoft earnings is over dependent on one major customer. Therefore, when the customer's business slows down, it will directly impacted the company's earning. 
  • Customers are mainly in Malaysia (Elsoft should explore more into overseas market).
  • According to its 2018 AGM, its current factory utilization rate is merely 50% only as its major customer business slows down due to trade war. 


Valuation @ RM 0.805
  • From the above info, we can see that Elsoft's EPS started to go downhill after reaching a peak of 2.06 sen in Q3 2018 due to the uncertainty in trade war. Its latest quarter's EPS further deteriorate to 0.73 sen and expected to be slower for Q2 2019 according to the management prospect in 2018 annual report and will only recover slightly in 2nd half of 2019. 
  • Assuming if Elsoft generates EPS of 1.5 sen for the first half of 2019 and EPS of 2.5 sen for 2nd half of 2019, Elsoft would have a total of EPS of 4 sen for FY 2019. At current price of RM 0.805, its PE will be 20 which is deemed to be fairly valued. 
  • Elsoft have a history of dividend payout ratio of approximately 75% and this translates into a dividend pay out of 3 sen for FY 2019. At current price of RM 0.805, its DY is 3.7%. 
  • I will just use the average PE of 16 to value Elsoft. Assuming a 4 sen of EPS full year, at PE 16, Elsoft is worth RM 0.64 and its DY will be 4.6%. So anything below RM 0.64, there will be a margin of safety. 


Technical Analysis


Elsoft is currently trading in a downtrend and has break below its trend-line at 0.83. Short term traders are advice to enter above 0.83. 


Saturday, June 1, 2019

Aeon Credit Service (M) Berhad ( AR 2019)

Corporate Profile


  • Listed on Kuala Lumpur Stock Exchange on 2007. 
    • In 2009, its revenue and net profit were RM 146 million and RM 48 million respectively. Share price after the bonus issue is RM 1.30
    • In 2019, its revenue and net profit were RM 1,365 million and RM 354 million respectively. Share price after the bonus issue is RM 16.30
    • Its revenue grew approximately 9 times while its profit grew approximately 7 times over the 10 years. Share price increased by 12 times over the 10 years. 
  • Aeoncr has won "highest return on equity over 3 years", "highest growth in profit before tax over 3 years" continuously for year 2015 , 2016 , 2017 , 2018 for the edge award for financial service sector under RM 10 billion market capital. (This has proven that Aeoncr has consistency create values for its shareholders over the past 5 years)
  • From the above cover page of 2019 annual report, we can see that Aeoncr is currently focusing on its cashless wallet to join the trend of e-wallet (i am not too sure how will this benefit Aeoncr greatly)
  • Prior to 2018, the market segment that Aeoncr target is always the low income customers. However in 2018, they Launched AEON Platinum credit card (Visa and MasterCard) which is targeting at middle income customers. The minimum salary to apply for the card is RM 60,000 per annum. (this segment of customer usually has lower default risk in my opinion)
  • Aeoncr also successfully obtain money lending license valid for 2 years ended in Jan 2021 (I believe Aeoncr can renew this license after that). This license enable Aeoncr to undertake any business of those relating to the money lending activities which complements its existing business. (i believe this can be another growth phase for Aeoncr)
  • As at 2019, Aeoncr has 4.6 million of card members, 12,000 merchant outlet nationwide and 71 branches and service center. 
  • From the above info, we can see that Aeoncr derive its income from mainly car financing (30%) followed by motorcycle financing (28%) and personal financing (26%). Financing on motor vehicle and personal financing constitute 85% of its income. (People who failed to get a loan from the bank will usually approach Aeoncr for their loan). 
  • Aeoncr derive its main income from micro-financing.
  • 62.59% of its shares are hold by its mother company AEON FINANCIAL SERVICE CO. LTD. with the rest of its top 30 shareholders being foreign fund. 


Financial Highlight
  1. Revenue and net profit of Aeoncr grew at CAGR of 12% from 2014 - 2019 which is amazing as it beats the bank's performance. 
  2. The number of shares grew 78% due to RCULS conversion which causes its EPS to drop 23% from 2017 - 2019. Without the additional shares, Aeoncr actually did very well as its net profit grew 33% from 2017 - 2019.
  3. Dividend payout ratio stood at approximately 30 - 35%. 
  4. Gross financing receivables are the amount that Aeconcr borrowed out and yet to collect back. As you can see that its gross financing receivables and net financing receivables grew by CAGR of 16% and 14% respectively (meaning to say, the business become bigger). 
  5. Aeoncr achieved the lowest NPL over the 6 years which is only 2.04%.
  6. Its PEG ratio workout to be 0.91.


Future Prospect
  • Aeoncr will roll out the Robotic Process Automation and Biometric Identification which will benefit the Company in our operations and offer greater convenience to our customers.
  • Launched e-wallet in November 2018 (however i dont see its e-wallet being popular yet and not sure how it can help Aeoncr to make money?).
  • Trying to increase their middle income customer as currently 70% of their customers are the B40(low income group). 
  • Continue to strengthen its customers’ loyalty through the continuous introduction of new loyalty programmes and benefits.
  • Slowly move to B2B from B2C after obtaining the money lending license. 


Strength
  • It is difficult for low income group to get loan from the bank therefore, they will turn to Aeoncr for their loan. However, Aeoncr would need to make sure the quality of their customer to minimize the default risk. 
  • Strong management team as proven in the past 10 years (It is worth taking note that their NPL is only 2.04% which is even lower than CIMB of 2.91% and Maybank of 2.41%. Aeoncr customers' risk are usually higher than the conventional bank as they charge a higher interest rate for this default risk. However they are able to manage the risk to 2% is something worth praising)
  • Strong balance sheet with high ROE.


Weakness
  • Low dividend yield. 
  • There will be further EPS dilution as there are more ICULS to be converted. 


Valuation @ RM 16.10
  • At RM 16.10, its PE is 11.39 which is consider as its peak and its DY is only 2.77% which is below the 3% monthly FD rate. 
  • A fair PE for Aeoncr would be somewhere around 10. Assuming if its EPS remain flat due to further ICULS conversion for 2020, at PE 10, its share price is RM 13.58 and its DY would be 3.3%. 
  • At DY of 3%, its share price is RM 14.80. 


Technical Analysis

Aeoncr has been trading below its trendline for quite sometime however it is still well supported by its 200MA. Its 20MA is approaching to cross below its 200MA signifying the start of a downtrend if it happens. 

Friday, May 31, 2019

Amway Q1 2019

  • Gross profit margin and net profit margin of Amway shrink further to 23.81% and 4.29% from 24.71% and 5.61% respectively in 2018. 
  • Distribution, selling and administration expenses accounts for 18.6% in Q1 2019 as compared to 18.17% in 2018. 
  • From the above chart, we can see that USD/MYR dropped from January, February and March 2019 but still the margin of Amway shrink as compared to previous quarter? (not too sure about Amway hedging policy on USD). The average USD/MYR rate for Jan - Mar 2019 is 4.07
  • The management is optimistic that the sales will continue to grow as the management mentioned that they will increase their selling price effective March 2019. However, the profit margin might be under pressure due to unfavorable USD rate. 

Comments

For the moment, there is no sign of recovery for Amway yet as their gross profit margin is below its benchmark of 24.5%. USD is on the rise as well. Hopefully the increase in product price will mitigate their cost of import however will it be harder for its ABO to sales their product as it becomes more expensive? 

At current price RM 5.83, its PE is 16.77 which is the lowest since 2014 and its DY is 4.72%. Amway achieve an EPS of 6.5 sen for the quarter, assuming if Amway generates an EPS of 28 sen for 2019, at PE 18 - Amway is worth RM 5.04, at PE 20 - Amway is worth RM 5.60. 


Power Root Berhad (Annual Report 2019 & Q4 2020)

Company Background Pwroot is an instant drinks manufacturer with different brands to target different customers.  Ah Huat instan...